Natural News Store

Showing posts with label Timothy Geithner. Show all posts

Friday, July 10, 2009

Medvedev Unveils “World Currency” Coin At G8

Russian President shows reporters example of “united future world currency”
Medvedev Unveils World Currency Coin At G8 100709top2
Paul Joseph Watson
Prison Planet.com
Friday, July 10, 2009
In a highly symbolic moment at the G8 summit in Italy today, Russian President Dmitry Medvedev unveiled to reporters a coin representing a “united future world currency”.
“We are discussing both the use of other national currencies, including the ruble, as a reserve currency, as well as supranational currencies,” the Russian leader said at a news conference.
However, those who have downplayed the formulation of a world currency by dismissing it as merely a progression of SDR’s (Special Drawing Rights) and not something that would physically be used by citizens in a system of world government, were contradicted when Medvedev clearly outlined that the new currency would be “used for payment” by citizens as a “united future world currency”.
“This is a symbol of our unity and our desire to settle such issues jointly,” Medvedev said.
“Here it is,” Medvedev told reporters today in L’Aquila, Italy, after a summit of the Group of Eight nations. “You can see it and touch it,” reports Bloomberg.
The question of a supranational currency “concerns everyone now, even the mints,” Medvedev said. The test coin “means they’re getting ready. I think it’s a good sign that we understand how interdependent we are.”
Press images released to the Yahoo photo wire did not show any close up shots of the coin and little was known about it, except that it had been minted in Belgium and bears the words “unity in diversity”. An RIA Novosti report noted that the coin represented an example of a “possible global currency”.
China and Russia have repeatedly called for a new global currency to replace the dollar.
When confronted about plans to supplant the dollar with a new global currency, both Federal Reserve chairman Ben Bernanke and Treasury Secretary Timothy Geithner denied that such an agenda existed.
However, just days after he told a Congressional hearing that there were no plans to move towards a global currency, Geithner sought to please the elitist CFR by assuring them that he was “open” to the notion of a new global currency system.
The scandal-ridden and highly secretive Bank For International Settlements, considered to be the world’s top central banking power hub, released a policy paper in 2006 that called for the end of national currencies in favor of a global model of currency formats.
The global currency would be a key central plank of a future system of world government. Earlier this week, Pope Benedict called for a “world political authority” to manage the global economy.

Monday, April 6, 2009

Never in the field of human history has so much been taken from so many by so few

Simon Davies & Donald Hunt
SOTT.net
Sat, 04 Apr 2009 19:39 UTC
 
© Credit Union
 
The last week in March started with the coordinated call from Russia and China for a new non-national reserve currency, an idea that was greeted as one would expect with some derision until US Treasury Secretary Timothy Geithner said he supported such an idea. We can only speculate that he forgot his role in this Act 2 of the international stage tragedy "Global Financial Crisis" and used his lines from Act 4 which has of course yet to come. In this Act the role of the US is to resist such calls.

The week ended with the G20 summit and more importantly with the G20 final communique which promises a dark future; for wrapped in the cloth of "free trade", a trillion dollars for the IMF and "trade finance" and the regulation of banker's pay is the formation of a global overseer, the Financial Stability Board and the announcement that "the era of banking secrecy (which means privacy) is over."

There is a great deal in the G20 final communique and what with the general goings on this coming week with the NATO summit following the G20 and US President Obama's visit to Ankara that we will be providing an analysis of the G20 summit and its context during the course of next week.

This week we take a closer look at who really benefited from the AIG bailout and the true size of the US governments financial commitments to the "Global Financial Crisis". With apologies to Winston Churchill and the fighter pilots of the Battle of Britain:-
Never in the field of human history has so much been taken from so many by so few
Markets

Since Tuesday, March 31st was the end of the first quarter of 2009, let's look at the quarterly numbers. The dollar gained ground in the first quarter, gaining 5% on the euro and 7.6% on the yen. The major world stock indices fell during the first quarter, with the Dow losing almost 16%, the FTSE 14%, the DAX 18%, the NIKKEI 8.5%, and the Hang Seng down 9.75%. The Brazilian BOVESPA was up 1.7%. Gold was up 5.5% in dollars and 11% in euros. Oil rose 7% in dollars and 12.6% in euros. [This week's and the quarter's data tables are at the end of this article].

For the week and two days since Friday, March 20th, world stock indices were up, mostly in the 2% to 6% range, as was the dollar (up 2.5% against the euro and 3% against the yen). Gold fell 3% and oil fell almost 5% in dollars.

Here are some charts following currency and commodity prices since January 2005. Note that oil prices and the dollar/euro exchange rates are very close to what they were in the beginning of '05. Gold, however, has more than doubled despite the immense downward pressure exerted by the world gold cartel as it seeks to maintain a cap on the price of gold and silver.


Dollar/Gold - note the ceiling at $1,000

Dollar/Oil - back to Jan 05 levels

Euro/Oil

Gold:Oil ratio - quite a change in a year!

Dollar/Euro
Reserve Currency

Some confusion was generated, deliberately or not, last week when U.S. Treasury Secretary Geithner told the Chinese that he was "quite open" to a new reserve currency besides the dollar.
The dollar plunged instantly against the euro, yen, and sterling as the comments flashed across trading screens. David Bloom, currency chief at HSBC, said the apparent policy shift amounts to an earthquake in geo-finance.

"The mere fact that the US Treasury Secretary is even entertaining thoughts that the dollar may cease being the anchor of the global monetary system has caused consternation," he said.

Mr Geithner later qualified his remarks, insisting that the dollar would remain the "world's dominant reserve currency ... for a long period of time" but the seeds of doubt have been sown.

The markets appear baffled by the confused statements emanating from Washington. President Barack Obama told a new conference hours earlier that there was no threat to the reserve status of the dollar.
What are we to make of this? As the Financial Times wrote, changing reserve currencies is quite an undertaking which ultimately hangs on "sovereign credibility and power":-
Global reserve currency

Athenian owls, Roman denarii, British sovereigns, US dollars. There have been many pseudo reserve currencies down the ages. Now the governor of the People's Bank of China has called for a new global currency "disconnected from individual nations". Russia, too, wants to move away from a world dominated by the dollar. Kazakh president Nursultan Nazarbayev suggests such a currency could be called the acmetal - an amalgam of "acme" and "capital".

But is there a case for one? In theory, yes. (Although no one was banging the table for change when emerging growth rates were still being powered by deliberately undervalued domestic currencies.) The reserve currency status of the dollar helped to create nasty global imbalances - one of the main culprits of the current downturn. As China, for example, recycled export earnings back into dollar-denominated assets, the US could happily run profligate trade deficits with impunity. That helped push up the price of US assets, particularly house prices.

Now surplus countries are stuck. They cannot diversify fast enough and a rapid sell down of US assets would destroy their portfolios. Not only that, global central banks holding about two thirds of their reserves in dollars are hostage to the Obama administration. Unsurprisingly, huge budget deficits and the Federal Reserve's leap into quantitative easing have foreigners fretting over the longer term health of the dollar.

Theory is one thing, however. In reality, currencies live and breathe more than just short-term economic air. The two other life forces for a reserve currency are sovereign credibility and power. China, Russia and India simply do not have long enough economic track records to justify backing a reserve currency. Find a single investor in this crisis that has panicked out of dollars into roubles. Of course, if China one day emerges as the dominant economic and military power, the status quo will change. Until then, investors cannot be rushed.
© Unknown
What the Financial Times seems to be avoiding is the obvious fact that the idea of a new international reserve currency means that it will be supra-national and the "power' and "credibility" will be delivered by a supra-national body or bodies. Such a body or group of bodies would have the effect of being a World Government.

One thing is clear, if destroying the dollar moves the Plan to concentrate control of the world into fewer hands, among which will be a handful of megabanks, it will happen; conversely, if the Plan calls for a strong dollar, that will happen. For the moment it appears that the confusion caused by Geithner's and China's statements was intended; or, as we said in our introduction, perhaps Geithner forgot which Act of the play we are in.

Gold

Once more we see gold being manipulated, this time ahead of the G20 summit being sold down aggressively to the $900 mark. At the summit we heard the same old tired story of IMF gold being sold into the physical market; a story that just keeps getting trotted out whenever the physical market looks likely to burst through the downward pressure exerted through the futures market.

Seeking Alpha has come across an interesting change in the futures market:-
NYSE Runs Out of Gold Bars: What Happens Next?

The NYSE-Liffe futures exchange has, it seems, run out of 1 kg bars of gold. Futures markets, like NYSE-Liffe and COMEX, try hard to maintain the fiction that they will deliver physical gold, [o]n completion of executed contracts. Indeed, to prevent fraud, U.S. law requires clearing members to keep a stockpile, of one kind or another, consisting of a minimum of 90% of metal. Up until October, 2008, it didn't matter. Only about 1% of long buyers of paper gold futures contracts typically took delivery. Now, the situation is very different. Demand has surged and, it appears, one major futures exchange, NYSE-Liffe, and by extension, the COMEX gold warehouses it shares with its larger cousin, are unable to meet the requirements of their contracts, vis-a-vis, delivery of 1 kg. bars.

As of December 31, 2008, the NYSE-Liffe mini-gold (YG) contract specifications were changed to read, in pertinent part, as follows:
33.2 fine troy ounces (+10%), no less than .995 fineness. Seller's discretion delivery of one vault receipt representing one bar or one Warehouse Depository Receipt (WDR) representing either 1/3 interest in one full size gold NYSE Liffe vault receipt or full interest in a NYSE Liffe Mini Gold vault receipt. Delivered to exchange approved vaults by exchange approved carriers.
But, before that, on August 26, 2008, it read as follows:
33.2 troy ounces (±5%) of refined gold, assaying not less than .995 fineness, contained in no more than one bar.
In summary, there is now so much demand for delivery of the mini-contracts that the exchange can no longer deliver 1 kg bars. When the wording was changed, a flurry of complaints resulted. Technically, in my opinion, if you bought a mini futures contract from an NYSE-Liffe clearing member, prior to December 31st, you could bind them to their legal contract with you, and force them to either deliver the 1 kg bar, or pay for you to obtain it on the open spot market. Based upon the original wording, NYSE-Liffe and its clearing members are legally obligated to deliver that 1 kg bar per contract, whether they want to or not, and regardless of the internal rules of the exchange. Whether anyone will force compliance, however, is an open question.
On top of this or perhaps because of it, COMEX has announced that it is launching a new E-Mini future contracts on gold and silver on April 19th covering, yes you guessed it, 1kg of gold and 1000oz of silver for which they is absolutely no mechanism for physical delivery. With no mechanism for delivery and only cash settlement the floodgates of market manipulation through naked short selling will be opened. Theodore Butler summed these new contracts up perfectly:-
Let me be as clear as I can - because these new contracts do not contain actual metal delivery clauses, they are, in my opinion, fraudulent contracts. The CME should be ashamed of itself for introducing them, and the CFTC disgraces itself (again) for not preventing their introduction.
With ever greater quantitative easing and the resulting inflationary pressures we can only wonder how long the blatant rigging of the bullion market can continue.

Monetary Policy, Inflation, Stimulus

If you are trying to keep score, according to Bloomberg, the U.S. has spent or committed almost $13 trillion on bailouts, rescues, and stimuli. Note the attitude displayed of the bankers and economist in the article below and ask yourself, with respect to each of them, if this is the attitude of a person who really understands what is going on, who hasn't a clue or is in on the scam:-
Financial Rescue Nears GDP as Pledges Top $12.8 Trillion

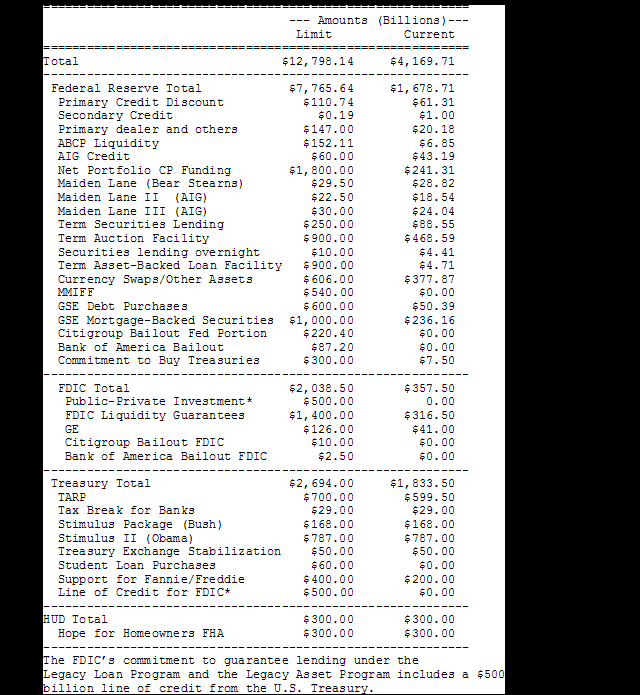
The U.S. government and the Federal Reserve have spent, lent or committed $12.8 trillion, an amount that approaches the value of everything produced in the country last year, to stem the longest recession since the 1930s.

New pledges from the Fed, the Treasury Department and the Federal Deposit Insurance Corp. include $1 trillion for the Public-Private Investment Program, designed to help investors buy distressed loans and other assets from U.S. banks. The money works out to $42,105 for every man, woman and child in the U.S. and 14 times the $899.8 billion of currency in circulation. The nation's gross domestic product was $14.2 trillion in 2008.

President Barack Obama and Treasury Secretary Timothy Geithner met with the chief executives of the nation's 12 biggest banks on March 27 at the White House to enlist their support to thaw a 20-month freeze in bank lending.

"The president and Treasury Secretary Geithner have said they will do what it takes," Goldman Sachs Group Inc. Chief Executive Officer Lloyd Blankfein said after the meeting. "If it is enough, that will be great. If it is not enough, they will have to do more."

Commitments include a $500 billion line of credit to the FDIC from the government's coffers that will enable the agency to guarantee as much as $2 trillion worth of debt for participants in the Term Asset-Backed Lending Facility and the Public-Private Investment Program. FDIC Chairman Sheila Bair warned that the insurance fund to protect customer deposits at U.S. banks could dry up because of bank failures.

'Within an Eyelash'

The combined commitment has increased by 73 percent since November, when Bloomberg first estimated the funding, loans and guarantees at $7.4 trillion.

"The comparison to GDP serves the useful purpose of underscoring how extraordinary the efforts have been to stabilize the credit markets," said Dana Johnson, chief economist for Comerica Bank in Dallas.

"Everything the Fed, the FDIC and the Treasury do doesn't always work out right but back in October we came within an eyelash of having a truly horrible collapse of our financial system, said Johnson, a former Fed senior economist. "They used their creativity to help the worst-case scenario from unfolding and I'm awfully glad they did it."

Federal Reserve officials project the economy will keep shrinking until at least mid-year, which would mark the longest U.S. recession since the Great Depression.

The following table details how the Fed and the government have committed the money on behalf of American taxpayers over the past 20 months, according to data compiled by Bloomberg.

The Real Economy

The recession in the UK was worse in the 4th quarter of 2008 than thought due to sharper decreases in consumer spending and construction.

In the United States, home prices fell 20% from January 2008 to January 2009 in the 20-city index published by Case Shiller. The city of Flint, Michigan, made famous by Michael Moore's classic documentary, Roger and Me, is actually considering shutting down parts of the city:-
Look in any direction from Bianca Bates' north Flint home, and you'll see graffiti-covered siding, boarded-up windows and overgrown lots

About half of the homes on her block are burned out or vacant magnets for drug dealers and squatters. It isn't where she thought she'd end up, but it's all she can afford to rent.

© Ryan Garza/The Flint Journal
The view through an abandoned house's broken window looks out on a boarded-up house across the street on East Russell Avenue in Flint.
"It's a dangerous place to live," said Bates, 21, who lives on East Russell Avenue. "Everywhere you look, these houses are empty around here."

Property abandonment is getting so bad in Flint that some in government are talking about an extreme measure that was once unthinkable -- shutting down portions of the city, officially abandoning them and cutting off police and fire service.

Temporary Mayor Michael Brown made the off-the-cuff suggestion Friday in response to a question at a Rotary Club of Flint luncheon about the thousands of empty houses in Flint.

Brown said that as more people abandon homes, eating away at the city's tax base and creating more blight, the city might need to examine "shutting down quadrants of the city where we (wouldn't) provide services."

He did not define what that could mean -- bulldozing abandoned areas, simply leaving the vacant homes to rot or some other idea entirely.

On Monday, a city spokesman downplayed Brown's comments.
US banking rescue

Just in case there was any doubt who is running the United States it was wiped away as President Obama had a "very pleasant" meeting with the big bankers then, a week later, fired the head of General Motors and condemned GM and Chrysler to bankruptcy. The auto companies actually make something useful and provide salaries, pensions and healthcare to lots of working and retired people while the banks have been shown to be nothing more than immense private casinos.

There is no doubt that the economic system needs to be restructured, banks and auto companies included, but to continue bailing banks out with essentially no conditionality other than a few figs leaves to placate the public while condemning the millions of people associated with the auto industry is reprehensible. Maybe the auto companies should have donated more money to the campaigns of the President and members of Congress.

Although after the meeting with the bankers, there was a show of some dissatisfaction, that was only for public display. Joe Kishore:-
Every aspect of the administration's economic policy caters to the interests of the financial elite, of which the president is merely a mouthpiece. The private meeting at the White House had the air of a conspiracy against the public, a gathering to discuss carving up state resources in order to hand them over to the banks and major investors.
The discussions about the auto industry revolved around how best to deny healthcare and pensions obligations to retired workers. When, after a massive giveaway to the banks, Obama had to appear tough against the corporate elite, he took on the politically easy target of the auto companies. Of course the auto companies are no angels having connived to suppress fuel-efficient and alternative fuel vehicles for decades and building their products on the basis of them being consumables rather than long term assets. But they are one of the few remaining pillars of manufacturing in the US with millions of livelihoods depending upon them. It takes years to retool auto plants so decisions taken now will be hard to reverse; which may be exactly the point of course.
© Mr. Fish

Joe Kishore again:-
As the administration works with Wall Street to make the banks - and the personal portfolios of the bankers - whole, Obama is preparing a massive attack on the working class. During his press conference, the president repeatedly stressed his determination to tackle "high health care costs" and implement "Entitlement reform" - i.e., cuts in Social Security, Medicare and Medicaid.

As the question of restrictions on executive bonuses is dropped, Obama repeated on Thursday his insistence that any aid to the auto industry be conditioned on further job and wage cuts from autoworkers. In an online town hall meeting, the president said that the auto industry will have to "make some pretty drastic changes. And some of those are still going to be painful."

The policy of the administration is to ensure that this "pain" is born entirely by the working class, while the looting of public assets by the financial elite continues.
The Geithner plan to take devote $1.2 trillion to take "toxic" assets off bank balance sheets is breathtaking in its criminal simplicity: use taxpayer money to pay banks for their worthless assets, leaving the banks to run their profitable businesses and keep the money they stole for over a decade. The scheme is headlined at $1.2 trillion which according to Douglas Elliot at the Brookings Institute is the sum total of toxic mortgage assets held by US banks. Not only that, but they get to run one more scam.
The Free Market, Financial Style: How the Scam Works

Newspaper reports seem surprised at how high banks are bidding for the junk mortgages that Treasury Secretary Geithner is now bidding for, having mobilized the FDIC and Fed to transfer yet more public funds to the banks. Bank stocks are soaring - thereby bidding up the Dow Jones Industrial Average, as if the "financial industry" really were part of the industrial economy.

Why are the very worst offenders - Bank of America (now owner of the Countrywide crooks) and Citibank the largest buyers? As the worst abusers and packagers of CDOs, shouldn't they be in the best position to see how worthless their junk mortgages are?

That turns out to be the key! Obviously, the government has failed to protect itself - deliberately, intentionally failed to do so - in order to let the banks pull off the following scam.

Suppose a bank is sitting on a $10 million package of collateralized debt obligations (CDOs) that was put together by, say, Countrywide out of junk mortgages. Given the high proportion of fraud (and a recent Fitch study found that every package it examined was rife with financial fraud), this package may be worth at most only $2 million as defaults loom on Alt-A "liars' loan" mortgages and sub-prime mortgages where the mortgage brokers also have lied in filling out the forms for hapless borrowers or witting operators taking out mortgages at far more than properties were worth and pocketing the excess.

The bank now offers $3 million to buy back this mortgage. What the hell, the more they bid, the more they get from the government. So why not bid $5 million. (In practice, friendly banks may bid for each other's junk CDOs.) The government - that is, the hapless FDIC - puts up 85 per cent of $5 million to buy this - namely, $4,250,000. The bank only needs to put up 15 per cent - namely, $750,000.

Here's the rip-off as I see it. For an outlay of $750,000, the bank rids its books of a mortgage worth $2 million, for which it receives $4,250,000. It gets twice as much as the junk is worth.

The more the banks holding junk mortgages pay for this toxic waste, the more the government will pay as part of its 85 per cent. So the strategy is to overpay, overpay, and overpay. Paying 15 per cent is a small price to pay for getting the government to put in 85 per cent to take the most toxic waste off your books.

The free market at work, financial style.
© Unknown
Wanted for fiscal crimes against humanity: Henry 'Hank' Paulson, former Treasury Secretary and CEO of Goldman Sachs
What Michael Hudson, author the article above, has skimmed over is that the scam is even bigger than he describes so succinctly. According to Elliot at the Brookings Institute; the private investors (the banks, hedge funds and private equity funds) will have their losses capped at 10 to 20 percent of what they put up; the Fed will come in 50/50 on the meagre amount the investor puts up and on occasion will lend the entire investment amount. The scheme is astounding in depth and breadth; it is a trillion dollar heist.

AIG and Goldman Sachs

Talking of scams and heists, as we discussed last week, the grandstanding in the US Congress over AIG bonuses was clearly designed for the media spin machine while deftly keeping the real secrets of the AIG bailout out of the public mind. As Megan Slack at Alternet points out, the Merrill Lynch "performance related" bonuses were 22 times the contractual "retention" bonuses at AIG. The Merrill bonuses were also 36.2% of the TARP monies granted to Merrill and Bank of America, it's new parent. We may have missed it of course but we didn't notice the roof of Congress being blown off in uproar and hastily cobbled tax Bills being rushed through at the Merrill pay outs. It is therefore appropriate to take a close look at where some of the AIG bailout money went.

Last week we explored how AIG Financial Products (AIGFP) acted as final insurer for an array of Credit Default Swaps and other unregulated derivatives in a manner that meant that when the value of the insured securities dropped AIGFP was required to provide cash collateral. AIGFP was also heavily involved in the Stock Lending business which included similar arrangements for AIGFP to provide cash collateral in the event of the value of stocks falling. On March 15th AIG disclosed who its counterparties were and how much money they had received under these collateral and other arrangements between September 16th 2008 and December 31st 2008.

Setting aside the sums paid to US States, we find that $22.4 billion was paid out directly as collateral against Credit Default Swaps; $27.1 billion indirectly, via a company set up to manage parts of the AIGFP portfolio called Maiden Lane III, as collateral against Credit Default Swaps; and $43 billion to Securities Lending Counterparties, all to banks.

The individual beneficiaries of note were; Goldman Sachs - $12.9 billion, Bank of America/Merrill Lynch - $ 12.4 billion, Societe Generale $11.9 billion, Deutsche Bank - $11.8 billion, Barclays - $8.5 billion, UBS - $ 5 billion and BNP Paribas - $4.9 billion.

Of course complete silence over where all this money went was impossible. Initial calls for investigation came from those who champion global markets when it suits the US and then suddenly find themselves violently opposed to global markets when it doesn't suit. The initial wave of protectionist rhetoric focused on the fact that foreigners were reaping the benefits of the AIG bailout but this has now had to be broadened to include Goldman Sachs.
AIG Payments to Banks Should Be Probed, Lawmakers Say

Lawmakers called for a federal probe into whether banks including Goldman Sachs Group Inc. received more funds than necessary from the bailout of American International Group Inc.

"We would like to know if the AIG counterparty payments, as made, were in the best interests of the taxpayers," said 27 members of Congress led by Elijah Cummings, a Democrat from Maryland, in a letter dated yesterday to Neil Barofsky, inspector general for the Troubled Asset Relief Program. Banks got about $50 billion in payments tied to credit-default swaps.

The demand reflects widening frustration among lawmakers with the rising cost of AIG's bailout, now valued at $182.5 billion. The U.S. has propped up New York-based AIG four times since September after a cash shortage left the insurer unable to back up protection sold to banks on their fixed-income holdings. The lawmakers asked why banks weren't asked to take some losses to help stabilize AIG and the financial system.

"Was any attempt made to renegotiate and close out these contracts with 'haircuts?'" the letter asked. "If not, why not?"

The query from the lawmakers concerns payments made to unwind some of AIG's credit-default swaps, contracts similar to insurance that pay investors if bonds don't pay as promised. AIG sold swaps to more than 20 U.S. and foreign banks.

Imposing 'Haircuts'

After AIG was rescued by the U.S. from collapse last year, banks that bought credit-default swaps got $22.4 billion in collateral and $27.1 billion in payments to retire the contracts, the insurer said earlier this month. Goldman Sachs, Deutsche Bank AG and Societe Generale SA were among the largest recipients. The letter asked whether holders received 100 cents on the dollar for their securities, a sum they wouldn't be entitled to get unless their bonds actually defaulted...
© Unknown
So in summary we have a group of international banks who have made billions from the trading of securities, often through the deliberate and careful manipulation of prudential and legal regulation, finding that the value of their portfolios was severely reduced due to a mixture of factors including the simple fact that many of the securities were in fact useless junk. Other securities may not be useless junk but nobody can really tell as they depend upon ordinary people paying their mortgages and companies paying their loan commitments over time.

Under the law, the banks would have to sit out the crisis and see what could be recovered over time. Their insurer is bankrupt and cannot be relied upon as it is insolvent and must therefore be wound up. Whether they recover 5 cents on the dollar or more or less will be a matter of time and a great deal of hassle. If this was the insurance on our homes, our assets or our life savings this is what would happen.

But the law does not apply to the financial elite; other rules apply to them.

Before moving on let's cast our minds back to September 2008 when Lehman had collapsed, AIG was rescued and the New York Times ran this story:-
Behind Insurer's Crisis, Blind Eye to a Web of Risk

Although it was not widely known, Goldman, a Wall Street stalwart that had seemed immune to its rivals' woes, was A.I.G.'s largest trading partner, according to six people close to the insurer who requested anonymity because of confidentiality agreements. A collapse of the insurer threatened to leave a hole of as much as $20 billion in Goldman's side, several of these people said.

Days later, federal officials, who had let Lehman die and initially balked at tossing a lifeline to A.I.G., ended up bailing out the insurer for $85 billion.

Their message was simple: Lehman was expendable. But if A.I.G. unspooled, so could some of the mightiest enterprises in the world.

A Goldman spokesman said in an interview that the firm was never imperiled by A.I.G.'s troubles and that Mr. Blankfein participated in the Fed discussions to safeguard the entire financial system, not his firm's own interests.
As FTAlphaville put it:-
... which caused something of a furore.

Goldman strenuously and very publicly denied the gist of the allegation. So aggressive was their rebuttal, in fact, that the wires even wrote up separate stories on it. Here's Reuters:
Goldman Sachs Group Inc rejected as "seriously misleading" a published report on Sunday that said the Wall Street bank had as much as $20 billion of exposure to the troubled insurance giant American International Group Inc.

Lucas van Praag, a Goldman spokesman, on Sunday said the Times article was wrong to suggest that Goldman had reason to be concerned about AIG's problems.

"Although we have said many times on the record that our exposure to AIG was, and is, not material, the reporter chose to pursue a story line which suggests, by innuendo, that is not the case," he said in an e-mailed statement.

"For the avoidance of doubt, our exposure to AIG is offset by collateral and hedges and is not material to Goldman Sachs in any way," he continued. "The conclusions about our interests that readers of the New York Times article are invited to reach are seriously misleading."
© M. Spencer Green/AP
Now, being humble souls we at Sott.net may not have a proper understanding of the value of money but doesn't $12.9 billion seem like a material amount of money to you?

At the end of 2008 Goldman Sachs had $42.7 billion of Tangible Common Equity (TCE - the type of core capital that the Obama administration is focused on), should AIG not have paid out that $12.9 billion the hit for Goldman would have been taken against this. Such a significant hit to a bank's capital in the current environment might have been catastrophic. What Goldman has collected between the end of 2008 and now under the ever increasing AIG bailout is anybody's guess.

Not only is $12.9 billion a material amount of money and banking capital but the last time one of us did a stock exchange exam it was a criminal offensive to make false or misleading statements in relation to a public company, especially if the person making those statements was an officer of the company. So it seems to us that members of the US Congress instead of grandstanding for punitive taxes against AIGFP executives should be demanding criminal probes of Goldman Sachs and its current and former employees. This is of course not going to happen because Goldman Sachs former employees run the US government. What an excellent example of the corporate controlled state, otherwise known as Fascism.

To believe that the financial crisis is a result of mistakes or stupidity would be naïve. Larry Summers, Timothy Geithner and their colleagues are not stupid. Nor, more importantly, are the faceless people giving them their orders. The mess the whole world is in is a direct and completely foreseeable result of the legal and regulatory framework put in place with the commencement of the repeal of the Glass-Steagall Act in 1999. Dave Lindorff dug up quotes from the 1999 article about the repeal in the New York Times:
A Financial History Lesson: These Are the People We Expect to Fix Things?

George Santayana once famously said, "Those who cannot learn from history are doomed to repeat it." But what about those who don't just ignore history, but who hire and take counsel from those who committed historic follies in the past?

Back in November 1999, Congress passed legislation pushed by then Sen. Phil Gramm (R-TX), rescinding the Depression-era Glass-Steagall Act. The measure, backed by the Clinton administration, and overwhelmingly passed by the Senate (90-8) and the House (362-57), opened the way for banks to merge with investment banks and insurance companies, and led directly to the current financial cataclysm.

A report on that Congressional action written by reporter Stephen Labaton and published in the New York Times on Nov. 5, 1999 under the headline "Congress Passes Wide-Ranging Bill Easing Bank Laws," includes some remarkable quotes from key players in that sellout to the financial sector.

Here's Larry Summers, a chief architect of the current financial industry multi-trillion-dollar bailout giveaway being orchestrated by the Obama administration, where he serves as director of President Obama's National Economic Council:-
''Today Congress voted to update the rules that have governed financial services since the Great Depression and replace them with a system for the 21st century. This historic legislation will better enable American companies to compete in the new economy.''
And here's what Sen. Charles Schumer (D-NY), awash in Financial industry campaign donations but currently in high dudgeon over the Wall Street's bonus payments to executives, speaking about the '99 measure eliminating Glass-Steagall:-
''If we don't pass this bill, we could find London or Frankfurt or years down the road Shanghai becoming the financial capital of the world. There are many reasons for this bill, but first and foremost is to ensure that U.S. financial firms remain competitive."
The article quotes the Clinton administration and Summers' Treasury Department as predicting that revoking Glass-Steagall and permitting banks to expand into investment banking and insurance would save consumers "$18 billion a year" through economies of scale - a figure that seems rather quaint as taxpayers now pony up trillions of dollars to rescue those same institutions. (The article notes that critics of deregulation argued that even those paltry savings, probably overstated, would flow to financial sector investors, not to consumers.)

The old Times clip (brought to my attention by alert veteran radical writer and activist Bert Schultz of Philadelphia), does highlight a couple of prophetic heroes, too.

Sen. Byron Dorgan (D-ND), one of seven Senate Democrats who voted against revoking Glass-Steagall, said:-
"I think we will look back in 10 years' time and say we should not have done this but we did because we forgot the lessons of the past, and that that which is true in the 1930's is true in 2010. I wasn't around during the 1930's or the debate over Glass-Steagall. But I was here in the early 1980's when it was decided to allow the expansion of savings and loans. We have now decided in the name of modernization to forget the lessons of the past, of safety and of soundness.''
And then there's the late Sen. Paul Wellstone (D-MN), who died in a plane crash during his campaign for re-election in 2002. Congress, he said, seemed:-
"...determined to unlearn the lessons from our past mistakes. Scores of banks failed in the Great Depression as a result of unsound banking practices, and their failure only deepened the crisis. Glass-Steagall was intended to protect our financial system by insulating commercial banking from other forms of risk. It was one of several stabilizers designed to keep a similar tragedy from recurring. Now Congress is about to repeal that economic stabilizer without putting any comparable safeguard in its place.''
For the record, also voting against Glass-Steagall repeal in the Senate were lone Republican Richard Shelby of Alabama, and six other Democrats: Barbara Boxer (CA), Richard Bryan (NV), Russ Feingold (WI), Tom Harkin (IO), and Barbara Mikulski (MD). 51 Democrats, 5 Republicans and 1 independent voted against the measure in the House.

Treasury Secretary Tim Geithner, a key player in the current bailout scheme, isn't mentioned in the Times article about Glass-Steagall, but at the time was a protégé of Summers, working as undersecretary of the treasury for international affairs.

While they are thankfully well out of the loop in the current scramble in Washington to both end the reverse the economic collapse and try and help financial companies and financiers profit from it, it's worth reading too in this 10-year-old clip what Phil Gram and then Sen. Bob Kerry (D-NB and now embattled president of the New School in New York City) had to say about ending Glass-Steagall.

Sen. Gramm:-
'The world changes, and we have to change with it. We have a new century coming, and we have an opportunity to dominate that century the same way we dominated this century. Glass-Steagall, in the midst of the Great Depression, came at a time when the thinking was that the government was the answer. In this era of economic prosperity, we have decided that freedom is the answer.''
And then Sen. [Bob] Kerry, with a line that should probably be etched someday on his tombstone as his most memorable line:-
"The concerns that we will have a meltdown like 1929 are dramatically overblown."
The New York Times article did say that
The decision to repeal the Glass-Steagall Act of 1933 provoked dire warnings from a handful of dissenters that the deregulation of Wall Street would someday wreak havoc on the nation's financial system. The original idea behind Glass-Steagall was that separation between bankers and brokers would reduce the potential conflicts of interest that were thought to have contributed to the speculative stock frenzy before the Depression.
As always, we would all have been served better if the "handful of dissenters" had been listened to. However, we believe that the policymakers quoted in favor of the Act did realize what the consequences would be; they knew that it would open the flood gates of financial speculation known in banking as "proprietary trading"; their subsequent actions in allowing excessive bank leverage, keeping credit derivatives deliberately unregulated and emasculating the SEC and other regulators confirms this. They were lying to the public and they were conducting a scam in favour of the financial elite and themselves.

Under a Guise

With its President, Nicholas Sarkozy threatening to boycott the G20 summit, a threat so ridiculous in its hollowness that it was clearly stage-managed for the media spin machine, France is presented as being at the forefront of the push for tougher regulation and in the battle against 'tax havens'.

© Unknown
As we have commented before, there is nothing in the nature of this manufactured crisis that can be laid at the door of 'tax havens' yet Sarkozy makes it one of his "red line" principles upon which he is prepared to sacrifice the entire G20 summit. For Sarkozy this is a "red line" issue; for us this is a very large red flag for it seems that there are global moves afoot to establish totalitarianism. France and Germany are championing the destruction of financial privacy under the guise of fighting tax evasion; the EU as a whole is championing the replacement of parents with the state in the minds and lives of children; the UK is championing the destruction of privacy in general in its mania for video, email, postal and telephone surveillance under the guise of fighting terrorism; Australia is championing wholesale national censorship of the internet (the last free and open medium of exchange) under the guise of fighting terrorism and pedophilia; the US is championing the violence of the police state and total population control with its heavy use of Tasers, establishment of internment camps, "in-your-face policing" and "papers please" control that would make the Gestapo proud (in fact, if one traces the real origins of the CIA it IS making the Gestapo proud for that is the origin of much of the CIA); while Israel perfects the art of apartheid and genocide while portraying itself as the ultimate victim.

Each of these planks of the totalitarian future is being "perfected" and normalized in one country or region and then slowly introduced elsewhere. So while people, including yourself perhaps, may sit back and nod sagely that it is important to crush tax havens and prevent those dreadful tax evaders from evading their legal obligations remember that they are supporting a key part of the totalitarian future.

Sarkozy got what he wanted on tax havens in text that should be chilling for us all:-
..to take action against non-cooperative jurisdictions, including tax havens. We stand ready to deploy sanctions to protect our public finances and financial systems. The era of banking secrecy is over. We note that the OECD has today published a list of countries assessed by the Global Forum against the international standard for exchange of tax information;
In case it needs repeating, we urge you to truly understand what is meant by "non-cooperation" and the threat of sanctions. Remember that Iraq and Afghanistan are both sovereign nations that did not cooperate. Iraq was subject to sanctions that killed an estimated 500,000 children under 5 over ten years. Iran is a sovereign nation that is deemed by its enemies to not be cooperating and is now under a throttling regime of sanctions that go mostly unreported in the mainstream media.

There is a new world order being implemented both right in front of us and in the shadows; those that resist are termed "non-cooperative" and will have the full weight of propaganda turned against them such that should they continue to resist then sanctions will be imposed. For nations that rely on international finance for their survival, sanctions will no doubt bring them to heel; for other nations more brutal measures may be required, as in Iraq and Afghanistan. Every move will be justified using the mainstream media propaganda machine; the aggressors will be portrayed, as always, as seeking to right the wrongs of the world; all the while the dark suppressive blanket of totalitarianism is drawn further over us all.

The power of the nations of the G20 is essentially absolute so once again we see history marching forward forgetting the lessons of its past and in particular the old adage that "Power Corrupts and Absolute Power Corrupts Absolutely".

Market Data


The markets from March 23rd to March 31st

Previous close March 31st close Change % change
Gold (USD) 952.90 925.00 27.90 2.93%
Gold (EUR) 701.80 698.06 3.74 0.53%
Oil (USD) 52.10 49.66 2.44 4.68%
Oil (EUR) 38.37 37.48 0.89 2.33%
Gold:Oil 18.29 18.63 0.34 1.84%
USD / EUR 0.7365 / 1.3578 0.7547 / 1.3251 0.0182 / 0.0327 2.47% / 2.41%
USD / GBP 0.6918 / 1.4455 0.6982 / 1.4323 0.0064 / 0.0132 0.93% / 0.91%
USD / JPY 95.857/ 0.0104 98.82/ 0.0101 2.963 / 0.0003 3.09% / 2.88%
DOW 7,278 7,609 331 4.54%
FTSE 3,843 3,926 83 2.17%
DAX 4,069 4,085 16 0.39%
NIKKEI 7,946 8,110 164 2.06%
BOVESPA 40,076 40,926 849 2.12%
HANG SENG 12,834 13,576 743 5.79%
US Fed Funds 0.19% 0.31% 0.12 n/a
$ 3month 0.20% 0.20% 0.00 n/a
$ 10 year 2.64% 2.66% 0.02 n/a


The markets from January 2nd to March 31st

January 2nd close March 31st close Change % change
Gold (USD) 876.80 925.00 48.20 5.50%
Gold (EUR) 629. 698.06 68.27 10.84%
Oil (USD) 46.35 49.66 3.31 7.14%
Oil (EUR) 33.29 37.48 4.19 12.58%
Gold:Oil 18.92 18.63 0.29 1.55%
USD / EUR 0.7183 / 1.3922 0.7547 / 1.3251 0.0364 / 0.0671 5.07% / 4.82%
USD / GBP 0.6874/ 1.4548 0.6982 / 1.4323 0.0108 / 0.0225 1.57% / 1.55%
USD / JPY 91.830/ 0.0109 98.82/ 0.0101 6.99 / 0.0008 7.61% / 7.34%
DOW 9,035 7,609 1,426 15.78%
FTSE 4,562 3,926 636 13.93%
DAX 4,973 4,085 888 17.86%
NIKKEI 8,860 8,110 750 8.47%
BOVESPA 40,244 40,926 682 1.69%
HANG SENG 15,043 13,576 1,467 9.75%
US Fed Funds 0.06% 0.31% 0.25 n/a
$ 3month 0.08% 0.20% 0.12 n/a
$ 10 year 2.37% 2.66% 0.29 n/a


http://www.sott.net/articles/show/180960-Never-in-the-field-of-human-history-has-so-much-been-taken-from-so-many-by-so-few


Tuesday, March 31, 2009

A Scary Corporate Coup Is Under Way -- We've Got to Stop It

I don't necessarily agree with all of this authors point of view, becuase I believe the Fed should be shut down along with its many arms of power, including the IRS, Social Security, etc., that we need to restore our Constitutional Republic and not a "Democracy" that was put in place after the U.S. went bankrupt, suspending the Constitution and our nation being tyrannically ruled under war powers that have been in place ever since.

I will put it out there none the less, because I see the value of allowing all points of view to be heard.

A Scary Corporate Coup Is Under Way -- We've Got to Stop It

By William Greider, TheNation.com. Posted March 31, 2009

If Wall Street gets its way, Washington will pass new "reforms" that consolidate power and ratify a corporate state.

Editor's Note: Click here to join the protest!

The Rip Off Must Be Stopped!

Big bankers ruined our economy and now they are gaming the political system so they can profit even more off the crisis they caused. They must be stopped.

On April 11th, 2009, the public will come out in cities across the country to express their frustration and disapproval with how our elected officials have handled the economic crisis. No one has been left unscathed; this protest is yours.

Sign AlterNet's pledge that you aren't going to let this rip-off happen and join New Way Forward's national protest on April 11.

***

A reassuring new story line is emanating from our leaders. I heard Rep. Barney Frank, D-Mass., chairman of the House Banking Committee, explain it. Then I read the same line in a Washington Post news story. That tells me people in high places are selling it.

Dynamic capitalism, they explain, invents ways to create greater wealth, but sometimes it goes a little too far. Then government has to step in to correct things. This need typically occurs every generation or so, all in a day's work.

The Obama administration is proposing "sweeping" new regulatory laws so capitalism can continue its good works.

The story makes disturbing current events sound practically normal. But what are the storytellers leaving out?

They aren't saying that this financial catastrophe was not merely an inevitable development of history but a manmade disaster. Greedheads on Wall Street did their part, but so did Washington. The reason we need new rules is that a generation of Democrats and Republicans systematically repealed or gutted the old ones -- the regulatory controls enacted 80 years ago to remedy the last breakdown of capitalism (better known as the Great Depression).

The White House executed a nifty two-step this week to re-educate the public and deflect anger. On Tuesday, Treasury Secretary Timothy Geithner relaunched the massive bailout of banking and finance. Knowing how unpopular this is with the people at large, Geithner followed on Thursday with his "sweeping" plans to re-regulate the bankers and financiers.

Whenever official plans are called "sweeping," it indicates that they really, really mean it this time.

Most Americans are not financial experts. It's very difficult, nearly impossible, for normal mortals to sort through the dense policy talk and conflicting opinions to figure out if the rhetoric of reform is real.

Confusion is widespread in the land. Most Americans want to believe this president is leading us out of the swamp, but how can they know? I say, trust your gut feelings. They are as reliable as the learned experts.’

Many Americans want to believe because they think that returning to "normal" means their decimated 401(k) retirement accounts might somehow recover the 30-40 percent that disappeared during the past year. If it takes monster bank bailouts to restore stock-market prices, let's have bailouts.

Good luck with that.

The Dow has regained 21 percent in two weeks of rallies, but I remind friends that steep, short bursts in the stock market do not foretell the future of the economy. Banks may be relieved of their losses without changing the general economic outlook. After the crash of 1929, there were occasional stock rallies, followed by fierce bears. It took 25 years (until 1954) for the Dow to regain its old peak.

Another way to assess the Obama plan for reform is ask: Who likes it? The verdict was swift and sure after Geithner's twin announcements. Wall Street likes it.

The blueprint for regulatory reforms was applauded by the Securities Industry and Financial Markets Association; the American Insurance Association; and the Private Equity Council, the trade group for the major private funds that will get public money and backup insurance to buy the banking system's rotten assets.

This could be born-again patriotism. Or it could be the animal appetites of financiers smelling gorgeous opportunity for returns.

This may be one of those moments where people can find some guidance from their moral convictions. They do not need to know all the details to ask simple questions.

Does the outline of what's happening to rescue major financial institutions seem morally wrong? Or is it justified by the larger necessities of the national predicament? Is the government insufficiently tough in demanding reciprocal commitments from the beneficiaries? Should Washington pursue larger structural changes in the banking system?

Trying to imagine alternatives to the bankers-first bailouts is a good place to start. What follows are suggestions I produced at the request of young people organizing demonstrations around the country for April 11. They call themselves A New Way Forward. I hope they light lots of bonfires.

This rough outline leaves out lots of particular regulatory issues, but the core goal of reform is to create a banking and financial system that serves the society and the economy, not the other way around.

Everything being done to rescue and restore the old order gets in the way of creating something truly new and valuable for the future. Those of us throwing logs in the path of the bailouts are dismissed as naysayers or worse, but the financial titans are trying to foreclose just solutions by stampeding Congress and the president to adopt ill-considered ideas.

If Wall Street gets its way, the "reforms" may further consolidate power and ratify a corporate state -- a grotesque hybrid that combines the worst aspects of socialism and capitalism.

The reform ideas announced by Geithner would plant the seeds by creating a "systemic risk" regulator, presumably the Federal Reserve, to oversee the largest, most politically adept banks and financial firms that qualify as "too big to fail." Capitalism, with its inherent tendency toward monopoly, would have the means to monopolize democracy (see my recent Washington Post article.)

My new book, Come Home, America, asks people to enunciate their versions of "patriotic realism."

That is the essence of an alternative vision: de-concentrate power, liberate people and smaller enterprises, workers and middle managers and investors, to help shape the country's future from many different perspectives. This is how democracy was supposed to work. It can again.

Some points I recommend people consider:

1. Euthanasia for insolvent banks. Transferring their losses to the public will not restore the trillions in capital the bankers helped destroy. It would merely relieve the banks, their creditors and shareholders of the pain.

Government must take control of the system to supervise a just unwinding of the mess -- whether we call it nationalization or something else. Handing out money and leaving bankers in control of how it's spent is nutty and morally wrong. People everywhere understand this. Only Washington seems oblivious to the irrationality of what it is attempting.

2. The Federal Reserve must be democratized and effectively stripped of its peculiar, anti-democratic status as an unaccountable island of power within the government. A new federal agency -- accountable to Congress and the president -- can be refashioned from the working parts of the Fed. Call it a central bank or something else, but its governing power must not rest with heavyweight bankers on the board of directors at the 12 regional banks. (To understand why, consider that the New York Federal Reserve Bank was headed until recently by Geithner.)

3. The reformed Fed would be stripped of its regulatory functions and confined to conducting monetary policy. A different section of the Treasury or a new free-standing regulatory agency can assume responsibility for regulation and be armed with strong antitrust laws and other rules to ensure that "too big to fail" institutions are redefined as "too big to save."

4. The federal law against usury can be restored to halt predatory lending. Persistent violators would not be fined with trivial penalties, as they are now, but stripped of their government protections and subsidies -- that is, doomed.

5. A new banking system -- smaller and more diverse and responsible to the public interest -- can fill the hole left by the demise of major banks like Citigroup. Vast public resources should be devoted to creating this system, not to saving the mastodons. Public banks (like the North Dakota State Bank) and nonprofit savings-and-lending cooperatives can also serve as an important cross-check on private commercial banking -- a competitive model that offers credit on nonusurious terms and keeps the big boys honest.

6. Once the Federal Reserve is domesticated in a democratic fashion, then it can be reformed to assume broad supervision of the nonbank financial firms in the "shadow banking system" -- hedge funds, private equity firms, pension funds, mutual funds, insurance companies. (For more on this, see my recent Nation article, "Fixing the Fed.")

7. Our first political challenge is to disturb business as usual in Washington and prevent Congress from taking hasty action to adopt Wall Street's "reform" agenda. Congress is rattled by the exploding popular anger and listening nervously. The people need to speak louder -- loud enough for the president to hear.

William Greider is the author of, most recently, The Soul of Capitalism (Simon & Schuster).

http://www.alternet.org/democracy/134217/a_scary_corporate_coup_is_under_way_--_we%27ve_got_to_stop_it/

Monday, March 23, 2009

The Big Takeover: How Wall Street Insiders are Using the Bailout to Stage a Revolution

The rest of the nation is finally figuring out what we have already known...

By Matt Taibbi, RollingStone.com. Posted March 23, 2009.

The global economic crisis isn't about money -- it's about power.

This is part of a special AlterNet series on Obama's latest plans for a rescue of the bankers and Wall Street's toxic assets.
Read our editorial on the big picture.

Published by Rolling Stone

It's over - we're officially, royally fucked. No empire can survive being rendered a permanent laughingstock, which is what happened as of a few weeks ago, when the buffoons who have been running things in this country finally went one step too far. It happened when Treasury Secretary Timothy Geithner was forced to admit that he was once again going to have to stuff billions of taxpayer dollars into a dying insurance giant called AIG, itself a profound symbol of our national decline - a corporation that got rich insuring the concrete and steel of American industry in the country's heyday, only to destroy itself chasing phantom fortunes at the Wall Street card tables, like a dissolute nobleman gambling away the family estate in the waning days of the British Empire.

The latest bailout came as AIG admitted to having just posted the largest quarterly loss in American corporate history - some $61.7 billion. In the final three months of last year, the company lost more than $27 million every hour. That's $465,000 a minute, a yearly income for a median American household every six seconds, roughly $7,750 a second. And all this happened at the end of eight straight years that America devoted to frantically chasing the shadow of a terrorist threat to no avail, eight years spent stopping every citizen at every airport to search every purse, bag, crotch and briefcase for juice boxes and explosive tubes of toothpaste. Yet in the end, our government had no mechanism for searching the balance sheets of companies that held life-or-death power over our society and was unable to spot holes in the national economy the size of Libya (whose entire GDP last year was smaller than AIG's 2008 losses).

So it's time to admit it: We're fools, protagonists in a kind of gruesome comedy about the marriage of greed and stupidity. And the worst part about it is that we're still in denial - we still think this is some kind of unfortunate accident, not something that was created by the group of psychopaths on Wall Street whom we allowed to gang-rape the American Dream. When Geithner announced the new $30 billion bailout, the party line was that poor AIG was just a victim of a lot of shitty luck - bad year for business, you know, what with the financial crisis and all. Edward Liddy, the company's CEO, actually compared it to catching a cold: "The marketplace is a pretty crummy place to be right now," he said. "When the world catches pneumonia, we get it too." In a pathetic attempt at name-dropping, he even whined that AIG was being "consumed by the same issues that are driving house prices down and 401K statements down and Warren Buffet's investment portfolio down."

Liddy made AIG sound like an orphan begging in a soup line, hungry and sick from being left out in someone else's financial weather. He conveniently forgot to mention that AIG had spent more than a decade systematically scheming to evade U.S. and international regulators, or that one of the causes of its "pneumonia" was making colossal, world-sinking $500 billion bets with money it didn't have, in a toxic and completely unregulated derivatives market.

Nor did anyone mention that when AIG finally got up from its seat at the Wall Street casino, broke and busted in the afterdawn light, it owed money all over town - and that a huge chunk of your taxpayer dollars in this particular bailout scam will be going to pay off the other high rollers at its table. Or that this was a casino unique among all casinos, one where middle-class taxpayers cover the bets of billionaires.

People are pissed off about this financial crisis, and about this bailout, but they're not pissed off enough. The reality is that the worldwide economic meltdown and the bailout that followed were together a kind of revolution, a coup d'état. They cemented and formalized a political trend that has been snowballing for decades: the gradual takeover of the government by a small class of connected insiders, who used money to control elections, buy influence and systematically weaken financial regulations.

The crisis was the coup de grâce: Given virtually free rein over the economy, these same insiders first wrecked the financial world, then cunningly granted themselves nearly unlimited emergency powers to clean up their own mess. And so the gambling-addict leaders of companies like AIG end up not penniless and in jail, but with an Alien-style death grip on the Treasury and the Federal Reserve - "our partners in the government," as Liddy put it with a shockingly casual matter-of-factness after the most recent bailout.

The mistake most people make in looking at the financial crisis is thinking of it in terms of money, a habit that might lead you to look at the unfolding mess as a huge bonus-killing downer for the Wall Street class. But if you look at it in purely Machiavellian terms, what you see is a colossal power grab that threatens to turn the federal government into a kind of giant Enron - a huge, impenetrable black box filled with self-dealing insiders whose scheme is the securing of individual profits at the expense of an ocean of unwitting involuntary shareholders, previously known as taxpayers.

I. PATIENT ZERO

The best way to understand the financial crisis is to understand the meltdown at AIG. AIG is what happens when short, bald managers of otherwise boring financial bureaucracies start seeing Brad Pitt in the mirror. This is a company that built a giant fortune across more than a century by betting on safety-conscious policyholders - people who wear seat belts and build houses on high ground - and then blew it all in a year or two by turning their entire balance sheet over to a guy who acted like making huge bets with other people's money would make his dick bigger.

That guy - the Patient Zero of the global economic meltdown - was one Joseph Cassano, the head of a tiny, 400-person unit within the company called AIG Financial Products, or AIGFP. Cassano, a pudgy, balding Brooklyn College grad with beady eyes and way too much forehead, cut his teeth in the Eighties working for Mike Milken, the granddaddy of modern Wall Street debt alchemists. Milken, who pioneered the creative use of junk bonds, relied on messianic genius and a whole array of insider schemes to evade detection while wreaking financial disaster. Cassano, by contrast, was just a greedy little turd with a knack for selective accounting who ran his scam right out in the open, thanks to Washington's deregulation of the Wall Street casino. "It's all about the regulatory environment," says a government source involved with the AIG bailout. "These guys look for holes in the system, for ways they can do trades without government interference. Whatever is unregulated, all the action is going to pile into that."

The mess Cassano created had its roots in an investment boom fueled in part by a relatively new type of financial instrument called a collateralized-debt obligation. A CDO is like a box full of diced-up assets. They can be anything: mortgages, corporate loans, aircraft loans, credit-card loans, even other CDOs. So as X mortgage holder pays his bill, and Y corporate debtor pays his bill, and Z credit-card debtor pays his bill, money flows into the box.

The key idea behind a CDO is that there will always be at least some money in the box, regardless of how dicey the individual assets inside it are. No matter how you look at a single unemployed ex-con trying to pay the note on a six-bedroom house, he looks like a bad investment. But dump his loan in a box with a smorgasbord of auto loans, credit-card debt, corporate bonds and other crap, and you can be reasonably sure that somebody is going to pay up. Say $100 is supposed to come into the box every month. Even in an apocalypse, when $90 in payments might default, you'll still get $10. What the inventors of the CDO did is divide up the box into groups of investors and put that $10 into its own level, or "tranche." They then convinced ratings agencies like Moody's and S&P to give that top tranche the highest AAA rating - meaning it has close to zero credit risk.

Suddenly, thanks to this financial seal of approval, banks had a way to turn their shittiest mortgages and other financial waste into investment-grade paper and sell them to institutional investors like pensions and insurance companies, which were forced by regulators to keep their portfolios as safe as possible. Because CDOs offered higher rates of return than truly safe products like Treasury bills, it was a win-win: Banks made a fortune selling CDOs, and big investors made much more holding them.

The problem was, none of this was based on reality. "The banks knew they were selling crap," says a London-based trader from one of the bailed-out companies. To get AAA ratings, the CDOs relied not on their actual underlying assets but on crazy mathematical formulas that the banks cooked up to make the investments look safer than they really were. "They had some back room somewhere where a bunch of Indian guys who'd been doing nothing but math for God knows how many years would come up with some kind of model saying that this or that combination of debtors would only default once every 10,000 years," says one young trader who sold CDOs for a major investment bank. "It was nuts."

Now that even the crappiest mortgages could be sold to conservative investors, the CDOs spurred a massive explosion of irresponsible and predatory lending. In fact, there was such a crush to underwrite CDOs that it became hard to find enough subprime mortgages - read: enough unemployed meth dealers willing to buy million-dollar homes for no money down - to fill them all. As banks and investors of all kinds took on more and more in CDOs and similar instruments, they needed some way to hedge their massive bets - some kind of insurance policy, in case the housing bubble burst and all that debt went south at the same time. This was particularly true for investment banks, many of which got stuck holding or "warehousing" CDOs when they wrote more than they could sell. And that's were Joe Cassano came in.

Known for his boldness and arrogance, Cassano took over as chief of AIGFP in 2001. He was the favorite of Maurice "Hank" Greenberg, the head of AIG, who admired the younger man's hard-driving ways, even if neither he nor his successors fully understood exactly what it was that Cassano did. According to a source familiar with AIG's internal operations, Cassano basically told senior management, "You know insurance, I know investments, so you do what you do, and I'll do what I do - leave me alone." Given a free hand within the company, Cassano set out from his offices in London to sell a lucrative form of "insurance" to all those investors holding lots of CDOs. His tool of choice was another new financial instrument known as a credit-default swap, or CDS.

The CDS was popularized by J.P. Morgan, in particular by a group of young, creative bankers who would later become known as the "Morgan Mafia," as many of them would go on to assume influential positions in the finance world. In 1994, in between booze and games of tennis at a resort in Boca Raton, Florida, the Morgan gang plotted a way to help boost the bank's returns. One of their goals was to find a way to lend more money, while working around regulations that required them to keep a set amount of cash in reserve to back those loans. What they came up with was an early version of the credit-default swap.

In its simplest form, a CDS is just a bet on an outcome. Say Bank A writes a million-dollar mortgage to the Pope for a town house in the West Village. Bank A wants to hedge its mortgage risk in case the Pope can't make his monthly payments, so it buys CDS protection from Bank B, wherein it agrees to pay Bank B a premium of $1,000 a month for five years. In return, Bank B agrees to pay Bank A the full million-dollar value of the Pope's mortgage if he defaults. In theory, Bank A is covered if the Pope goes on a meth binge and loses his job.

When Morgan presented their plans for credit swaps to regulators in the late Nineties, they argued that if they bought CDS protection for enough of the investments in their portfolio, they had effectively moved the risk off their books. Therefore, they argued, they should be allowed to lend more, without keeping more cash in reserve. A whole host of regulators - from the Federal Reserve to the Office of the Comptroller of the Currency - accepted the argument, and Morgan was allowed to put more money on the street.

What Cassano did was to transform the credit swaps that Morgan popularized into the world's largest bet on the housing boom. In theory, at least, there's nothing wrong with buying a CDS to insure your investments. Investors paid a premium to AIGFP, and in return the company promised to pick up the tab if the mortgage-backed CDOs went bust. But as Cassano went on a selling spree, the deals he made differed from traditional insurance in several significant ways. First, the party selling CDS protection didn't have to post any money upfront. When a $100 corporate bond is sold, for example, someone has to show 100 actual dollars. But when you sell a $100 CDS guarantee, you don't have to show a dime. So Cassano could sell investment banks billions in guarantees without having any single asset to back it up.

Secondly, Cassano was selling so-called "naked" CDS deals. In a "naked" CDS, neither party actually holds the underlying loan. In other words, Bank B not only sells CDS protection to Bank A for its mortgage on the Pope - it turns around and sells protection to Bank C for the very same mortgage. This could go on ad nauseam: You could have Banks D through Z also betting on Bank A's mortgage. Unlike traditional insurance, Cassano was offering investors an opportunity to bet that someone else's house would burn down, or take out a term life policy on the guy with AIDS down the street. It was no different from gambling, the Wall Street version of a bunch of frat brothers betting on Jay Feely to make a field goal. Cassano was taking book for every bank that bet short on the housing market, but he didn't have the cash to pay off if the kick went wide.

In a span of only seven years, Cassano sold some $500 billion worth of CDS protection, with at least $64 billion of that tied to the subprime mortgage market. AIG didn't have even a fraction of that amount of cash on hand to cover its bets, but neither did it expect it would ever need any reserves. So long as defaults on the underlying securities remained a highly unlikely proposition, AIG was essentially collecting huge and steadily climbing premiums by selling insurance for the disaster it thought would never come.

Initially, at least, the revenues were enormous: AIGFP's returns went from $737 million in 1999 to $3.2 billion in 2005. Over the past seven years, the subsidiary's 400 employees were paid a total of $3.5 billion; Cassano himself pocketed at least $280 million in compensation. Everyone made their money - and then it all went to shit.

II. THE REGULATORS

Cassano's outrageous gamble wouldn't have been possible had he not had the good fortune to take over AIGFP just as Sen. Phil Gramm - a grinning, laissez-faire ideologue from Texas - had finished engineering the most dramatic deregulation of the financial industry since Emperor Hien Tsung invented paper money in 806 A.D. For years, Washington had kept a watchful eye on the nation's banks. Ever since the Great Depression, commercial banks - those that kept money on deposit for individuals and businesses - had not been allowed to double as investment banks, which raise money by issuing and selling securities. The Glass-Steagall Act, passed during the Depression, also prevented banks of any kind from getting into the insurance business.

But in the late Nineties, a few years before Cassano took over AIGFP, all that changed. The Democrats, tired of getting slaughtered in the fundraising arena by Republicans, decided to throw off their old reliance on unions and interest groups and become more "business-friendly." Wall Street responded by flooding Washington with money, buying allies in both parties. In the 10-year period beginning in 1998, financial companies spent $1.7 billion on federal campaign contributions and another $3.4 billion on lobbyists. They quickly got what they paid for. In 1999, Gramm co-sponsored a bill that repealed key aspects of the Glass-Steagall Act, smoothing the way for the creation of financial megafirms like Citigroup. The move did away with the built-in protections afforded by smaller banks. In the old days, a local banker knew the people whose loans were on his balance sheet: He wasn't going to give a million-dollar mortgage to a homeless meth addict, since he would have to keep that loan on his books. But a giant merged bank might write that loan and then sell it off to some fool in China, and who cared?

The very next year, Gramm compounded the problem by writing a sweeping new law called the Commodity Futures Modernization Act that made it impossible to regulate credit swaps as either gambling or securities. Commercial banks - which, thanks to Gramm, were now competing directly with investment banks for customers - were driven to buy credit swaps to loosen capital in search of higher yields. "By ruling that credit-default swaps were not gaming and not a security, the way was cleared for the growth of the market," said Eric Dinallo, head of the New York State Insurance Department.

The blanket exemption meant that Joe Cassano could now sell as many CDS contracts as he wanted, building up as huge a position as he wanted, without anyone in government saying a word. "You have to remember, investment banks aren't in the business of making huge directional bets," says the government source involved in the AIG bailout. When investment banks write CDS deals, they hedge them. But insurance companies don't have to hedge. And that's what AIG did. "They just bet massively long on the housing market," says the source. "Billions and billions."

In the biggest joke of all, Cassano's wheeling and dealing was regulated by the Office of Thrift Supervision, an agency that would prove to be defiantly uninterested in keeping watch over his operations. How a behemoth like AIG came to be regulated by the little-known and relatively small OTS is yet another triumph of the deregulatory instinct. Under another law passed in 1999, certain kinds of holding companies could choose the OTS as their regulator, provided they owned one or more thrifts (better known as savings-and-loans). Because the OTS was viewed as more compliant than the Fed or the Securities and Exchange Commission, companies rushed to reclassify themselves as thrifts. In 1999, AIG purchased a thrift in Delaware and managed to get approval for OTS regulation of its entire operation.

Making matters even more hilarious, AIGFP - a London-based subsidiary of an American insurance company - ought to have been regulated by one of Europe's more stringent regulators, like Britain's Financial Services Authority. But the OTS managed to convince the Europeans that it had the muscle to regulate these giant companies. By 2007, the EU had conferred legitimacy to OTS supervision of three mammoth firms - GE, AIG and Ameriprise.

That same year, as the subprime crisis was exploding, the Government Accountability Office criticized the OTS, noting a "disparity between the size of the agency and the diverse firms it oversees." Among other things, the GAO report noted that the entire OTS had only one insurance specialist on staff - and this despite the fact that it was the primary regulator for the world's largest insurer!

"There's this notion that the regulators couldn't do anything to stop AIG," says a government official who was present during the bailout. "That's bullshit. What you have to understand is that these regulators have ultimate power. They can send you a letter and say, 'You don't exist anymore,' and that's basically that. They don't even really need due process. The OTS could have said, 'We're going to pull your charter; we're going to pull your license; we're going to sue you.' And getting sued by your primary regulator is the kiss of death."

When AIG finally blew up, the OTS regulator ostensibly in charge of overseeing the insurance giant - a guy named C.K. Lee - basically admitted that he had blown it. His mistake, Lee said, was that he believed all those credit swaps in Cassano's portfolio were "fairly benign products." Why? Because the company told him so. "The judgment the company was making was that there was no big credit risk," he explained. (Lee now works as Midwest region director of the OTS; the agency declined to make him available for an interview.)

In early March, after the latest bailout of AIG, Treasury Secretary Timothy Geithner took what seemed to be a thinly veiled shot at the OTS, calling AIG a "huge, complex global insurance company attached to a very complicated investment bank/hedge fund that was allowed to build up without any adult supervision." But even without that "adult supervision," AIG might have been OK had it not been for a complete lack of internal controls. For six months before its meltdown, according to insiders, the company had been searching for a full-time chief financial officer and a chief risk-assessment officer, but never got around to hiring either. That meant that the 18th-largest company in the world had no one checking to make sure its balance sheet was safe and no one keeping track of how much cash and assets the firm had on hand. The situation was so bad that when outside consultants were called in a few weeks before the bailout, senior executives were unable to answer even the most basic questions about their company - like, for instance, how much exposure the firm had to the residential-mortgage market.

III. THE CRASH

Ironically, when reality finally caught up to Cassano, it wasn't because the housing market crapped but because of AIG itself. Before 2005, the company's debt was rated triple-A, meaning he didn't need to post much cash to sell CDS protection: The solid creditworthiness of AIG's name was guarantee enough. But the company's crummy accounting practices eventually caused its credit rating to be downgraded, triggering clauses in the CDS contracts that forced Cassano to post substantially more collateral to back his deals.

By the fall of 2007, it was evident that AIGFP's portfolio had turned poisonous, but like every good Wall Street huckster, Cassano schemed to keep his insane, Earth-swallowing gamble hidden from public view. That August, balls bulging, he announced to investors on a conference call that "it is hard for us, without being flippant, to even see a scenario within any kind of realm of reason that would see us losing $1 in any of those transactions." As he spoke, his CDS portfolio was racking up $352 million in losses. When the growing credit crunch prompted senior AIG executives to re-examine its liabilities, a company accountant named Joseph St. Denis became "gravely concerned" about the CDS deals and their potential for mass destruction. Cassano responded by personally forcing the poor sap out of the firm, telling him he was "deliberately excluded" from the financial review for fear that he might "pollute the process."

The following February, when AIG posted $11.5 billion in annual losses, it announced the resignation of Cassano as head of AIGFP, saying an auditor had found a "material weakness" in the CDS portfolio. But amazingly, the company not only allowed Cassano to keep $34 million in bonuses, it kept him on as a consultant for $1 million a month. In fact, Cassano remained on the payroll and kept collecting his monthly million through the end of September 2008, even after taxpayers had been forced to hand AIG $85 billion to patch up his fuck-ups. When asked in October why the company still retained Cassano at his $1 million-a-month rate despite his role in the probable downfall of Western civilization, CEO Martin Sullivan told Congress with a straight face that AIG wanted to "retain the 20-year knowledge that Mr. Cassano had." (Cassano, who is apparently hiding out in his lavish town house near Harrods in London, could not be reached for comment.)

What sank AIG in the end was another credit downgrade. Cassano had written so many CDS deals that when the company was facing another downgrade to its credit rating last September, from AA to A, it needed to post billions in collateral - not only more cash than it had on its balance sheet but more cash than it could raise even if it sold off every single one of its liquid assets. Even so, management dithered for days, not believing the company was in serious trouble. AIG was a dried-up prune, sapped of any real value, and its top executives didn't even know it.

On the weekend of September 13th, AIG's senior leaders were summoned to the offices of the New York Federal Reserve. Regulators from Dinallo's insurance office were there, as was Geithner, then chief of the New York Fed. Treasury Secretary Hank Paulson, who spent most of the weekend preoccupied with the collapse of Lehman Brothers, came in and out. Also present, for reasons that would emerge later, was Lloyd Blankfein, CEO of Goldman Sachs. The only relevant government office that wasn't represented was the regulator that should have been there all along: the OTS.

"We sat down with Paulson, Geithner and Dinallo," says a person present at the negotiations. "I didn't see the OTS even once."

On September 14th, according to another person present, Treasury officials presented Blankfein and other bankers in attendance with an absurd proposal: "They basically asked them to spend a day and check to see if they could raise the money privately." The laughably short time span to complete the mammoth task made the answer a foregone conclusion. At the end of the day, the bankers came back and told the government officials, gee, we checked, but we can't raise that much. And the bailout was on.

A short time later, it came out that AIG was planning to pay some $90 million in deferred compensation to former executives, and to accelerate the payout of $277 million in bonuses to others - a move the company insisted was necessary to "retain key employees." When Congress balked, AIG canceled the $90 million in payments.

Then, in January 2009, the company did it again. After all those years letting Cassano run wild, and after already getting caught paying out insane bonuses while on the public till, AIG decided to pay out another $450 million in bonuses. And to whom? To the 400 or so employees in Cassano's old unit, AIGFP, which is due to go out of business shortly! Yes, that's right, an average of $1.1 million in taxpayer-backed money apiece, to the very people who spent the past decade or so punching a hole in the fabric of the universe!

"We, uh, needed to keep these highly expert people in their seats," AIG spokeswoman Christina Pretto says to me in early February.

"But didn't these 'highly expert people' basically destroy your company?" I ask.

Pretto protests, says this isn't fair. The employees at AIGFP have already taken pay cuts, she says. Not retaining them would dilute the value of the company even further, make it harder to wrap up the unit's operations in an orderly fashion.

The bonuses are a nice comic touch highlighting one of the more outrageous tangents of the bailout age, namely the fact that, even with the planet in flames, some members of the Wall Street class can't even get used to the tragedy of having to fly coach. "These people need their trips to Baja, their spa treatments, their hand jobs," says an official involved in the AIG bailout, a serious look on his face, apparently not even half-kidding. "They don't function well without them."

IV. THE POWER GRAB

So that's the first step in wall street's power grab: making up things like credit-default swaps and collateralized-debt obligations, financial products so complex and inscrutable that ordinary American dumb people - to say nothing of federal regulators and even the CEOs of major corporations like AIG - are too intimidated to even try to understand them. That, combined with wise political investments, enabled the nation's top bankers to effectively scrap any meaningful oversight of the financial industry. In 1997 and 1998, the years leading up to the passage of Phil Gramm's fateful act that gutted Glass-Steagall, the banking, brokerage and insurance industries spent $350 million on political contributions and lobbying. Gramm alone - then the chairman of the Senate Banking Committee - collected $2.6 million in only five years. The law passed 90-8 in the Senate, with the support of 38 Democrats, including some names that might surprise you: Joe Biden, John Kerry, Tom Daschle, Dick Durbin, even John Edwards.

The act helped create the too-big-to-fail financial behemoths like Citigroup, AIG and Bank of America - and in turn helped those companies slowly crush their smaller competitors, leaving the major Wall Street firms with even more money and power to lobby for further deregulatory measures. "We're moving to an oligopolistic situation," Kenneth Guenther, a top executive with the Independent Community Bankers of America, lamented after the Gramm measure was passed.

The situation worsened in 2004, in an extraordinary move toward deregulation that never even got to a vote. At the time, the European Union was threatening to more strictly regulate the foreign operations of America's big investment banks if the U.S. didn't strengthen its own oversight. So the top five investment banks got together on April 28th of that year and - with the helpful assistance of then-Goldman Sachs chief and future Treasury Secretary Hank Paulson - made a pitch to George Bush's SEC chief at the time, William Donaldson, himself a former investment banker. The banks generously volunteered to submit to new rules restricting them from engaging in excessively risky activity. In exchange, they asked to be released from any lending restrictions. The discussion about the new rules lasted just 55 minutes, and there was not a single representative of a major media outlet there to record the fateful decision.

Donaldson OK'd the proposal, and the new rules were enough to get the EU to drop its threat to regulate the five firms. The only catch was, neither Donaldson nor his successor, Christopher Cox, actually did any regulating of the banks. They named a commission of seven people to oversee the five companies, whose combined assets came to total more than $4 trillion. But in the last year and a half of Cox's tenure, the group had no director and did not complete a single inspection. Great deal for the banks, which originally complained about being regulated by both Europe and the SEC, and ended up being regulated by no one.

Once the capital requirements were gone, those top five banks went hog-wild, jumping ass-first into the then-raging housing bubble. One of those was Bear Stearns, which used its freedom to drown itself in bad mortgage loans. In the short period between the 2004 change and Bear's collapse, the firm's debt-to-equity ratio soared from 12-1 to an insane 33-1. Another culprit was Goldman Sachs, which also had the good fortune, around then, to see its CEO, a bald-headed Frankensteinian goon named Hank Paulson (who received an estimated $200 million tax deferral by joining the government), ascend to Treasury secretary.

Freed from all capital restraints, sitting pretty with its man running the Treasury, Goldman jumped into the housing craze just like everyone else on Wall Street. Although it famously scored an $11 billion coup in 2007 when one of its trading units smartly shorted the housing market, the move didn't tell the whole story. In truth, Goldman still had a huge exposure come that fateful summer of 2008 - to none other than Joe Cassano.

Goldman Sachs, it turns out, was Cassano's biggest customer, with $20 billion of exposure in Cassano's CDS book. Which might explain why Goldman chief Lloyd Blankfein was in the room with ex-Goldmanite Hank Paulson that weekend of September 13th, when the federal government was supposedly bailing out AIG.

When asked why Blankfein was there, one of the government officials who was in the meeting shrugs. "One might say that it's because Goldman had so much exposure to AIGFP's portfolio," he says. "You'll never prove that, but one might suppose."

Market analyst Eric Salzman is more blunt. "If AIG went down," he says, "there was a good chance Goldman would not be able to collect." The AIG bailout, in effect, was Goldman bailing out Goldman.

Eventually, Paulson went a step further, elevating another ex-Goldmanite named Edward Liddy to run AIG - a company whose bailout money would be coming, in part, from the newly created TARP program, administered by another Goldman banker named Neel Kashkari.

V. REPO MEN

There are plenty of people who have noticed, in recent years, that when they lost their homes to foreclosure or were forced into bankruptcy because of crippling credit-card debt, no one in the government was there to rescue them. But when Goldman Sachs - a company whose average employee still made more than $350,000 last year, even in the midst of a depression - was suddenly faced with the possibility of losing money on the unregulated insurance deals it bought for its insane housing bets, the government was there in an instant to patch the hole. That's the essence of the bailout: rich bankers bailing out rich bankers, using the taxpayers' credit card.

The people who have spent their lives cloistered in this Wall Street community aren't much for sharing information with the great unwashed. Because all of this shit is complicated, because most of us mortals don't know what the hell LIBOR is or how a REIT works or how to use the word "zero coupon bond" in a sentence without sounding stupid - well, then, the people who do speak this idiotic language cannot under any circumstances be bothered to explain it to us and instead spend a lot of time rolling their eyes and asking us to trust them.

That roll of the eyes is a key part of the psychology of Paulsonism. The state is now being asked not just to call off its regulators or give tax breaks or funnel a few contracts to connected companies; it is intervening directly in the economy, for the sole purpose of preserving the influence of the megafirms. In essence, Paulson used the bailout to transform the government into a giant bureaucracy of entitled assholedom, one that would socialize "toxic" risks but keep both the profits and the management of the bailed-out firms in private hands. Moreover, this whole process would be done in secret, away from the prying eyes of NASCAR dads, broke-ass liberals who read translations of French novels, subprime mortgage holders and other such financial losers.

Some aspects of the bailout were secretive to the point of absurdity. In fact, if you look closely at just a few lines in the Federal Reserve's weekly public disclosures, you can literally see the moment where a big chunk of your money disappeared for good. The H4 report (called "Factors Affecting Reserve Balances") summarizes the activities of the Fed each week. You can find it online, and it's pretty much the only thing the Fed ever tells the world about what it does. For the week ending February 18th, the number under the heading "Repurchase Agreements" on the table is zero. It's a significant number.

Why? In the pre-crisis days, the Fed used to manage the money supply by periodically buying and selling securities on the open market through so-called Repurchase Agreements, or Repos. The Fed would typically dump $25 billion or so in cash onto the market every week, buying up Treasury bills, U.S. securities and even mortgage-backed securities from institutions like Goldman Sachs and J.P. Morgan, who would then "repurchase" them in a short period of time, usually one to seven days. This was the Fed's primary mechanism for controlling interest rates: Buying up securities gives banks more money to lend, which makes interest rates go down. Selling the securities back to the banks reduces the money available for lending, which makes interest rates go up.

If you look at the weekly H4 reports going back to the summer of 2007, you start to notice something alarming. At the start of the credit crunch, around August of that year, you see the Fed buying a few more Repos than usual - $33 billion or so. By November, as private-bank reserves were dwindling to alarmingly low levels, the Fed started injecting even more cash than usual into the economy: $48 billion. By late December, the number was up to $58 billion; by the following March, around the time of the Bear Stearns rescue, the Repo number had jumped to $77 billion. In the week of May 1st, 2008, the number was $115 billion - "out of control now," according to one congressional aide. For the rest of 2008, the numbers remained similarly in the stratosphere, the Fed pumping as much as $125 billion of these short-term loans into the economy - until suddenly, at the start of this year, the number drops to nothing. Zero.

The reason the number has dropped to nothing is that the Fed had simply stopped using relatively transparent devices like repurchase agreements to pump its money into the hands of private companies. By early 2009, a whole series of new government operations had been invented to inject cash into the economy, most all of them completely secretive and with names you've never heard of. There is the Term Auction Facility, the Term Securities Lending Facility, the Primary Dealer Credit Facility, the Commercial Paper Funding Facility and a monster called the Asset-Backed Commercial Paper Money Market Mutual Fund Liquidity Facility (boasting the chat-room horror-show acronym ABCPMMMFLF). For good measure, there's also something called a Money Market Investor Funding Facility, plus three facilities called Maiden Lane I, II and III to aid bailout recipients like Bear Stearns and AIG.

While the rest of America, and most of Congress, have been bugging out about the $700 billion bailout program called TARP, all of these newly created organisms in the Federal Reserve zoo have quietly been pumping not billions but trillions of dollars into the hands of private companies (at least $3 trillion so far in loans, with as much as $5.7 trillion more in guarantees of private investments). Although this technically isn't taxpayer money, it still affects taxpayers directly, because the activities of the Fed impact the economy as a whole. And this new, secretive activity by the Fed completely eclipses the TARP program in terms of its influence on the economy.

No one knows who's getting that money or exactly how much of it is disappearing through these new holes in the hull of America's credit rating. Moreover, no one can really be sure if these new institutions are even temporary at all - or whether they are being set up as permanent, state-aided crutches to Wall Street, designed to systematically suck bad investments off the ledgers of irresponsible lenders.

"They're supposed to be temporary," says Paul-Martin Foss, an aide to Rep. Ron Paul. "But we keep getting notices every six months or so that they're being renewed. They just sort of quietly announce it."

None other than disgraced senator Ted Stevens was the poor sap who made the unpleasant discovery that if Congress didn't like the Fed handing trillions of dollars to banks without any oversight, Congress could apparently go fuck itself - or so said the law. When Stevens asked the GAO about what authority Congress has to monitor the Fed, he got back a letter citing an obscure statute that nobody had ever heard of before: the Accounting and Auditing Act of 1950. The relevant section, 31 USC 714(b), dictated that congressional audits of the Federal Reserve may not include "deliberations, decisions and actions on monetary policy matters." The exemption, as Foss notes, "basically includes everything." According to the law, in other words, the Fed simply cannot be audited by Congress. Or by anyone else, for that matter.

VI. WINNERS AND LOSERS

Stevens isn't the only person in Congress to be given the finger by the Fed. In January, when Rep. Alan Grayson of Florida asked Federal Reserve vice chairman Donald Kohn where all the money went - only $1.2 trillion had vanished by then - Kohn gave Grayson a classic eye roll, saying he would be "very hesitant" to name names because it might discourage banks from taking the money.

"Has that ever happened?" Grayson asked. "Have people ever said, 'We will not take your $100 billion because people will find out about it?'"

"Well, we said we would not publish the names of the borrowers, so we have no test of that," Kohn answered, visibly annoyed with Grayson's meddling.

Grayson pressed on, demanding to know on what terms the Fed was lending the money. Presumably it was buying assets and making loans, but no one knew how it was pricing those assets - in other words, no one knew what kind of deal it was striking on behalf of taxpayers. So when Grayson asked if the purchased assets were "marked to market" - a methodology that assigns a concrete value to assets, based on the market rate on the day they are traded - Kohn answered, mysteriously, "The ones that have market values are marked to market." The implication was that the Fed was purchasing derivatives like credit swaps or other instruments that were basically impossible to value objectively - paying real money for God knows what.

"Well, how much of them don't have market values?" asked Grayson. "How much of them are worthless?"

"None are worthless," Kohn snapped.

"Then why don't you mark them to market?" Grayson demanded.

"Well," Kohn sighed, "we are marking the ones to market that have market values."

In essence, the Fed was telling Congress to lay off and let the experts handle things. "It's like buying a car in a used-car lot without opening the hood, and saying, 'I think it's fine,'" says Dan Fuss, an analyst with the investment firm Loomis Sayles. "The salesman says, 'Don't worry about it. Trust me.' It'll probably get us out of the lot, but how much farther? None of us knows."

When one considers the comparatively extensive system of congressional checks and balances that goes into the spending of every dollar in the budget via the normal appropriations process, what's happening in the Fed amounts to something truly revolutionary - a kind of shadow government with a budget many times the size of the normal federal outlay, administered dictatorially by one man, Fed chairman Ben Bernanke. "We spend hours and hours and hours arguing over $10 million amendments on the floor of the Senate, but there has been no discussion about who has been receiving this $3 trillion," says Sen. Bernie Sanders. "It is beyond comprehension."

Count Sanders among those who don't buy the argument that Wall Street firms shouldn't have to face being outed as recipients of public funds, that making this information public might cause investors to panic and dump their holdings in these firms. "I guess if we made that public, they'd go on strike or something," he muses.

And the Fed isn't the only arm of the bailout that has closed ranks. The Treasury, too, has maintained incredible secrecy surrounding its implementation even of the TARP program, which was mandated by Congress. To this date, no one knows exactly what criteria the Treasury Department used to determine which banks received bailout funds and which didn't - particularly the first $350 billion given out under Bush appointee Hank Paulson.

The situation with the first TARP payments grew so absurd that when the Congressional Oversight Panel, charged with monitoring the bailout money, sent a query to Paulson asking how he decided whom to give money to, Treasury responded - and this isn't a joke - by directing the panel to a copy of the TARP application form on its website. Elizabeth Warren, the chair of the Congressional Oversight Panel, was struck nearly speechless by the response.

"Do you believe that?" she says incredulously. "That's not what we had in mind."

Another member of Congress, who asked not to be named, offers his own theory about the TARP process. "I think basically if you knew Hank Paulson, you got the money," he says.

This cozy arrangement created yet another opportunity for big banks to devour market share at the expense of smaller regional lenders. While all the bigwigs at Citi and Goldman and Bank of America who had Paulson on speed-dial got bailed out right away - remember that TARP was originally passed because money had to be lent right now, that day, that minute, to stave off emergency - many small banks are still waiting for help. Five months into the TARP program, some not only haven't received any funds, they haven't even gotten a call back about their applications.

"There's definitely a feeling among community bankers that no one up there cares much if they make it or not," says Tanya Wheeless, president of the Arizona Bankers Association.

Which, of course, is exactly the opposite of what should be happening, since small, regional banks are far less guilty of the kinds of predatory lending that sank the economy. "They're not giving out subprime loans or easy credit," says Wheeless. "At the community level, it's much more bread-and-butter banking."

Nonetheless, the lion's share of the bailout money has gone to the larger, so-called "systemically important" banks. "It's like Treasury is picking winners and losers," says one state banking official who asked not to be identified.

This itself is a hugely important political development. In essence, the bailout accelerated the decline of regional community lenders by boosting the political power of their giant national competitors.

Which, when you think about it, is insane: What had brought us to the brink of collapse in the first place was this relentless instinct for building ever-larger megacompanies, passing deregulatory measures to gradually feed all the little fish in the sea to an ever-shrinking pool of Bigger Fish. To fix this problem, the government should have slowly liquidated these monster, too-big-to-fail firms and broken them down to smaller, more manageable companies. Instead, federal regulators closed ranks and used an almost completely secret bailout process to double down on the same faulty, merger-happy thinking that got us here in the first place, creating a constellation of megafirms under government control that are even bigger, more unwieldy and more crammed to the gills with systemic risk.

In essence, Paulson and his cronies turned the federal government into one gigantic, half-opaque holding company, one whose balance sheet includes the world's most appallingly large and risky hedge fund, a controlling stake in a dying insurance giant, huge investments in a group of teetering megabanks, and shares here and there in various auto-finance companies, student loans, and other failing businesses. Like AIG, this new federal holding company is a firm that has no mechanism for auditing itself and is run by leaders who have very little grasp of the daily operations of its disparate subsidiary operations.

In other words, it's AIG's rip-roaringly shitty business model writ almost inconceivably massive - to echo Geithner, a huge, complex global company attached to a very complicated investment bank/hedge fund that's been allowed to build up without adult supervision. How much of what kinds of crap is actually on our balance sheet, and what did we pay for it? When exactly will the rent come due, when will the money run out? Does anyone know what the hell is going on? And on the linear spectrum of capitalism to socialism, where exactly are we now? Is there a dictionary word that even describes what we are now? It would be funny, if it weren't such a nightmare.

VII. YOU DON'T GET IT

The real question from here is whether the Obama administration is going to move to bring the financial system back to a place where sanity is restored and the general public can have a say in things or whether the new financial bureaucracy will remain obscure, secretive and hopelessly complex. It might not bode well that Geithner, Obama's Treasury secretary, is one of the architects of the Paulson bailouts; as chief of the New York Fed, he helped orchestrate the Goldman-friendly AIG bailout and the secretive Maiden Lane facilities used to funnel funds to the dying company. Neither did it look good when Geithner - himself a protégé of notorious Goldman alum John Thain, the Merrill Lynch chief who paid out billions in bonuses after the state spent billions bailing out his firm - picked a former Goldman lobbyist named Mark Patterson to be his top aide.

In fact, most of Geithner's early moves reek strongly of Paulsonism. He has continually talked about partnering with private investors to create a so-called "bad bank" that would systemically relieve private lenders of bad assets - the kind of massive, opaque, quasi-private bureaucratic nightmare that Paulson specialized in. Geithner even refloated a Paulson proposal to use TALF, one of the Fed's new facilities, to essentially lend cheap money to hedge funds to invest in troubled banks while practically guaranteeing them enormous profits.

God knows exactly what this does for the taxpayer, but hedge-fund managers sure love the idea. "This is exactly what the financial system needs," said Andrew Feldstein, CEO of Blue Mountain Capital and one of the Morgan Mafia. Strangely, there aren't many people who don't run hedge funds who have expressed anything like that kind of enthusiasm for Geithner's ideas.

As complex as all the finances are, the politics aren't hard to follow. By creating an urgent crisis that can only be solved by those fluent in a language too complex for ordinary people to understand, the Wall Street crowd has turned the vast majority of Americans into non-participants in their own political future. There is a reason it used to be a crime in the Confederate states to teach a slave to read: Literacy is power. In the age of the CDS and CDO, most of us are financial illiterates. By making an already too-complex economy even more complex, Wall Street has used the crisis to effect a historic, revolutionary change in our political system - transforming a democracy into a two-tiered state, one with plugged-in financial bureaucrats above and clueless customers below.

The most galling thing about this financial crisis is that so many Wall Street types think they actually deserve not only their huge bonuses and lavish lifestyles but the awesome political power their own mistakes have left them in possession of. When challenged, they talk about how hard they work, the 90-hour weeks, the stress, the failed marriages, the hemorrhoids and gallstones they all get before they hit 40.

"But wait a minute," you say to them. "No one ever asked you to stay up all night eight days a week trying to get filthy rich shorting what's left of the American auto industry or selling $600 billion in toxic, irredeemable mortgages to ex-strippers on work release and Taco Bell clerks. Actually, come to think of it, why are we even giving taxpayer money to you people? Why are we not throwing your ass in jail instead?"

But before you even finish saying that, they're rolling their eyes, because You Don't Get It. These people were never about anything except turning money into money, in order to get more money; valueswise they're on par with crack addicts, or obsessive sexual deviants who burgle homes to steal panties. Yet these are the people in whose hands our entire political future now rests.

Good luck with that, America. And enjoy tax season.

Matt Taibbi is a writer for Rolling Stone.

http://www.alternet.org/workplace/132859/the_big_takeover%3A_how_wall_street_insiders_are_using_the_bailout_to_stage_a_revolution/